

Kudos has partnered with CardRatings and Red Ventures for our coverage of credit card products. Kudos, CardRatings, and Red Ventures may receive a commission from card issuers. Kudos may receive commission from card issuers. Some of the card offers that appear on Kudos are from advertisers and may impact how and where card products appear on the site. Kudos tries to include as many card companies and offers as we are aware of, including offers from issuers that don't pay us, but we may not cover all card companies or all available card offers. You don't have to use our links, but we're grateful when you do!

How Many Credit Cards Should You Have?
September 27, 2026


The content on this page is accurate as of the posting date; however, some of the offers mentioned may have expired.
How Many Credit Cards Should You Have?
There is no ideal number of credit cards. Card count isn't one of the five FICO Score categories; what matters is how you use your cards, especially whether you pay on time and how much of your available credit you use. For many people, two or three cards that match their spending is plenty, as long as they can pay every balance on time.
For context, Experian data from June 2025 shows Americans have an average of 3.7 credit cards in regular use. Some people do well with one card, and others manage ten without trouble.


Does Having Too Many Credit Cards Hurt Your Credit Score?
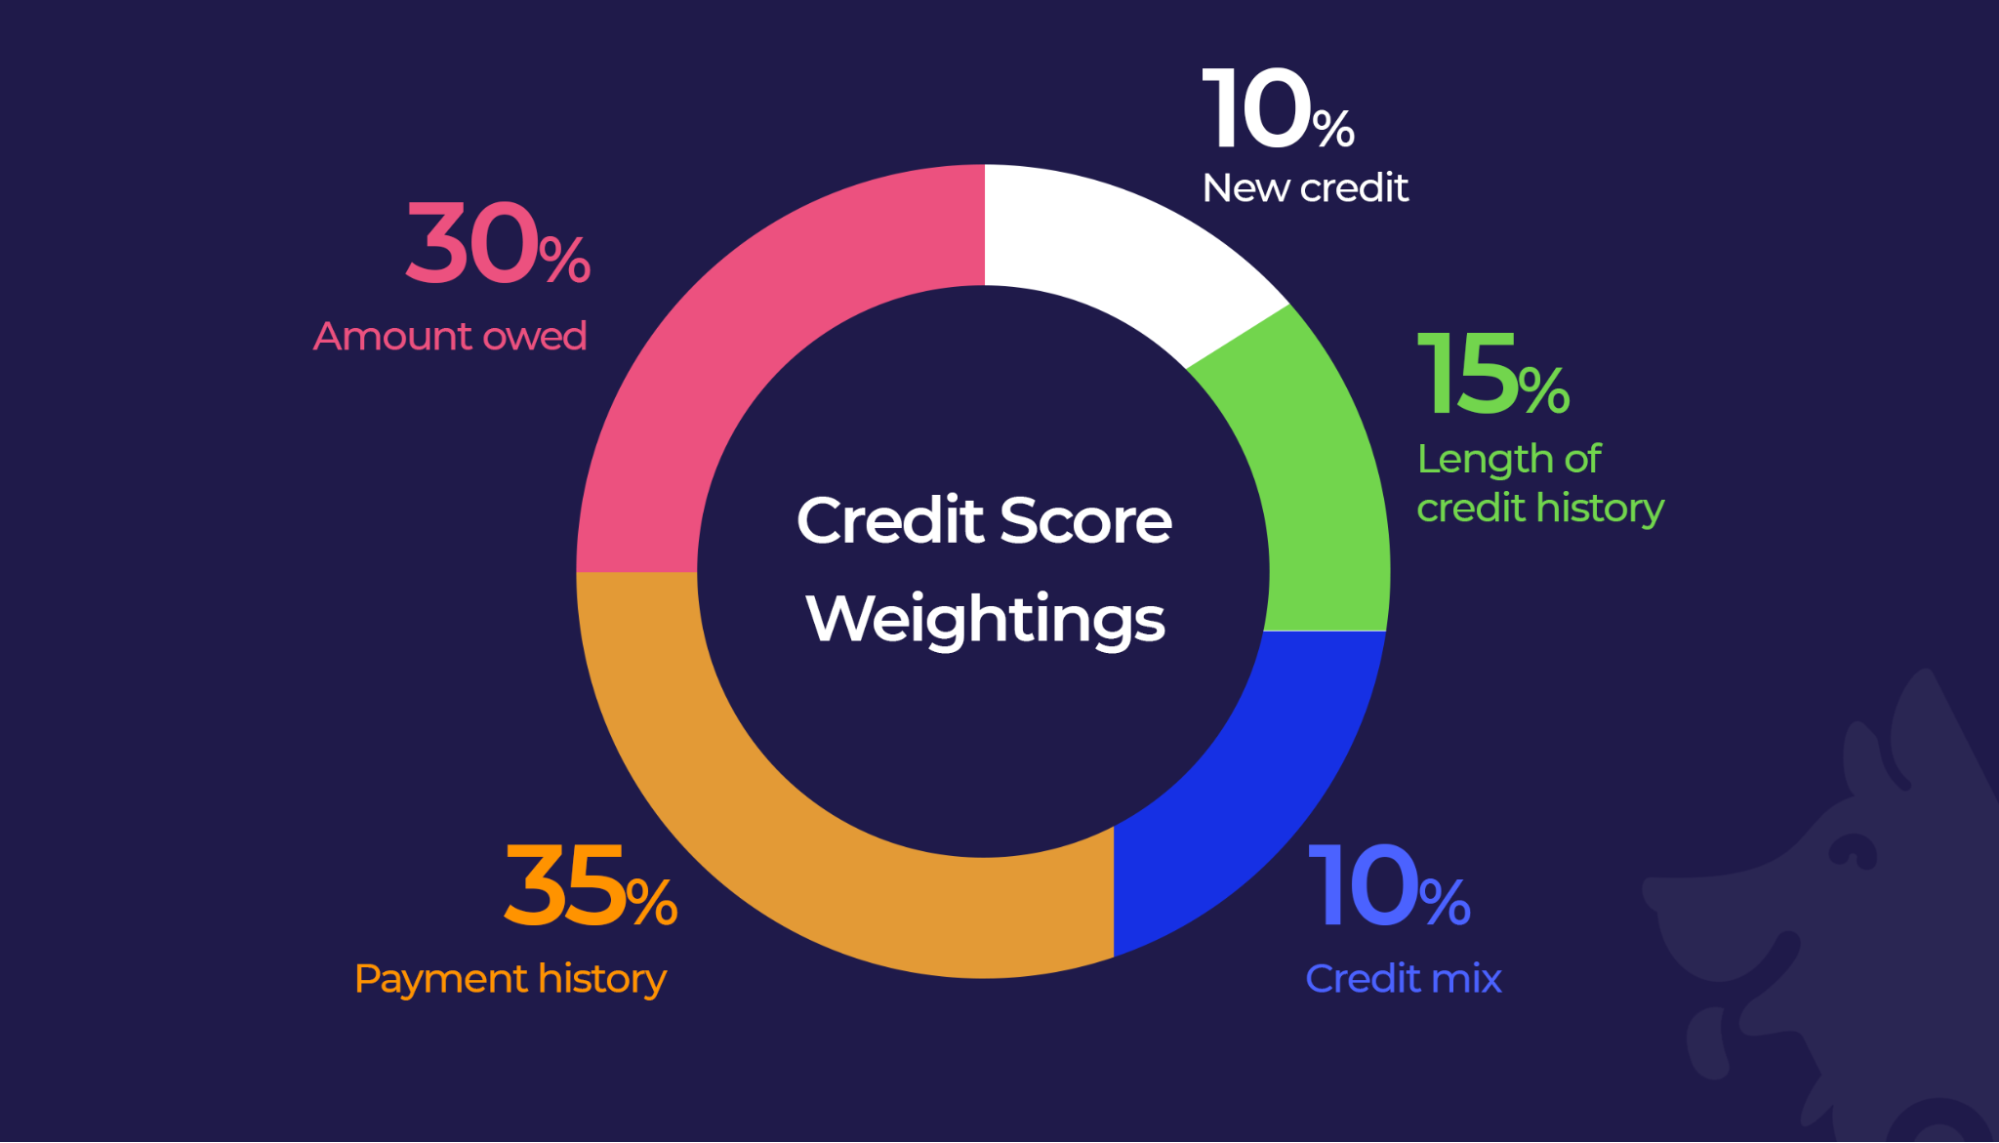
Not on its own. FICO Scores are built from five categories: payment history (35%), amounts owed (30%), length of credit history (15%), new credit (10%) and credit mix (10%). The number of cards you own isn't one of them, but how you manage those cards drives the two biggest categories.
Credit Utilization Matters More Than Card Count
Your credit utilization rate is your total card balances divided by your total credit limits. If you owe $1,000 across cards with $5,000 in combined limits, your utilization is 20%. myFICO notes that using a large share of your available credit can make lenders think you're overextended.
More cards can lower your utilization because they add to your total limit. With $2,700 in balances on $4,000 of limits, your utilization is 67.5%. Add a new card with a $1,000 limit and no balance, and it falls to 54%.
Calculation formulated by Kudos, based on total balances divided by total credit limits before and after adding a $1,000 limit with no balance.
See 6 ways to lower your credit card utilization rate for more tactics, and whether multiple credit cards help your credit score.
Do You Need Several Cards for a Good Credit Mix?
No. Credit mix counts for only 10% of a FICO Score, and myFICO says it isn't necessary to have one of each type of account. Paying on time and keeping balances low matter far more.

How Opening New Credit Cards Affects Your Score
Each application usually triggers a hard inquiry. According to myFICO, one new inquiry lowers FICO Scores by less than five points for most people, inquiries affect FICO Scores for one year, and they can stay on your credit report for up to two years.
Opening several accounts in a short period is a bigger concern. myFICO says it represents greater risk, especially for people with a short credit history, and new accounts also lower the average age of your accounts.
How Often Should You Apply for a New Card?
- Space out applications so inquiries and new accounts don't stack up at once.
- Hold off before a big loan. If you plan to apply for a mortgage or auto loan, avoid new cards in the months before.
- Know issuer rules. Some issuers look at how many cards you have opened recently. Our explainer on the Chase 5/24 rule covers one well-known example.
Learn more in our guide to hard vs. soft credit inquiries.
When Does Adding Another Credit Card Make Sense?
A new card is worth it when it adds something your current cards don't. Good reasons include:
- A higher rate where you spend the most, such as groceries, dining, gas or travel.
- A feature you need, like no foreign transaction fees before a trip or a 0% intro APR period for a large planned purchase.
- A welcome offer you can earn with normal spending, without buying things you don't need.
- A backup card in case your main card is lost or frozen.
The rewards gap between one card and a small set of cards can be meaningful. If you spend $2,000 a month on a card that earns a flat 2%, you earn $480 a year; moving $500 of monthly grocery spending to a card that earns 4% on groceries adds another $120.
Calculation formulated by Kudos, based on $24,000 in annual spending at a flat 2%, and $6,000 in annual grocery spending earning 4% instead of 2%.
If a card charges an annual fee, make sure the rewards and benefits you actually use cover it. Our guide to building a rewards strategy across multiple cards shows how to split spending, and types of credit cards explains the main categories.
Signs You Have Too Many Credit Cards
The right number is the most you can manage without slipping. You may have too many cards if:
- You've missed a payment or paid late because you lost track of due dates
- You carry balances and pay interest on more than one card
- Your annual fees add up to more than the value you get back
- Extra credit makes it easier to spend beyond your budget
Should You Close Cards You Don't Use?
Not always. Closing a card removes its limit from your available credit, which can raise your utilization if you carry balances elsewhere.
If an unused card has no annual fee, keeping it open and using it occasionally is often the simpler choice. Read more in does closing a credit card hurt your credit.
Pros and Cons of Having Multiple Credit Cards
Pros
- Can lower your credit utilization ratio
- Lets you earn higher rewards in more spending categories
- Gives you access to welcome offers and card benefits
- Provides a backup if one card is lost or frozen
Cons
- More due dates to track
- Potential for multiple annual fees
- New applications can temporarily lower your score
- Makes it easier to spend beyond your means


How Kudos Helps You Manage Multiple Cards
More cards only pay off if you use the right one each time. The free Kudos browser extension recommends the best card from your wallet at online checkout, keeps all your card rewards in one place, and lets you build a Dream Wallet to plan which cards to add next.
Before you apply, use the Kudos Card Explorer and approval odds to find cards that fill a real gap in your wallet. Kudos Premium adds a Benefits Tracker for card perks and subscription tracking with one-tap cancellation.
How Many Credit Cards Should I Have? FAQ
Is it bad to have 5 or more credit cards?
Not if you pay every bill on time and keep balances low. The risk is practical, not a scoring rule: more cards mean more due dates and more chances to overspend.
What is the average number of credit cards per person?
Experian data from June 2025 puts the average at 3.7 credit cards in regular use, meaning cards used or carrying a balance in the past six months.
Does the number of credit cards affect your credit score?
Not directly. FICO weighs payment history, amounts owed, length of credit history, new credit and credit mix. Card count affects your score indirectly through utilization, new inquiries and the average age of your accounts.
Is it bad to have only one credit card?
No. One card paid on time can build a solid credit history. The main drawback is that a single limit makes high utilization more likely if you run up a balance.
How long should you wait between credit card applications?
There's no official rule. Inquiries affect FICO Scores for a year, so spacing applications several months apart keeps their combined impact small and gives each new account time to age.
Unlock your extra benefits when you become a Kudos member


Turn your online shopping into even more rewards


Join over 500,000 members simplifying their finances


Editorial Disclosure: Opinions expressed here are those of Kudos alone, not those of any bank, credit card issuer, hotel, airline, or other entity. This content has not been reviewed, approved or otherwise endorsed by any of the entities included within the post.